Lottery Tax Calculator (2026): Lump Sum vs. Annuity Payout by State
Calculate precise net take-home winnings comparing your Day 1 Claim Center Payout Check against your Final Form 1040 & State Return Tax Reconciliation across all 50 U.S. states and municipal jurisdictions for the 2026 tax year.
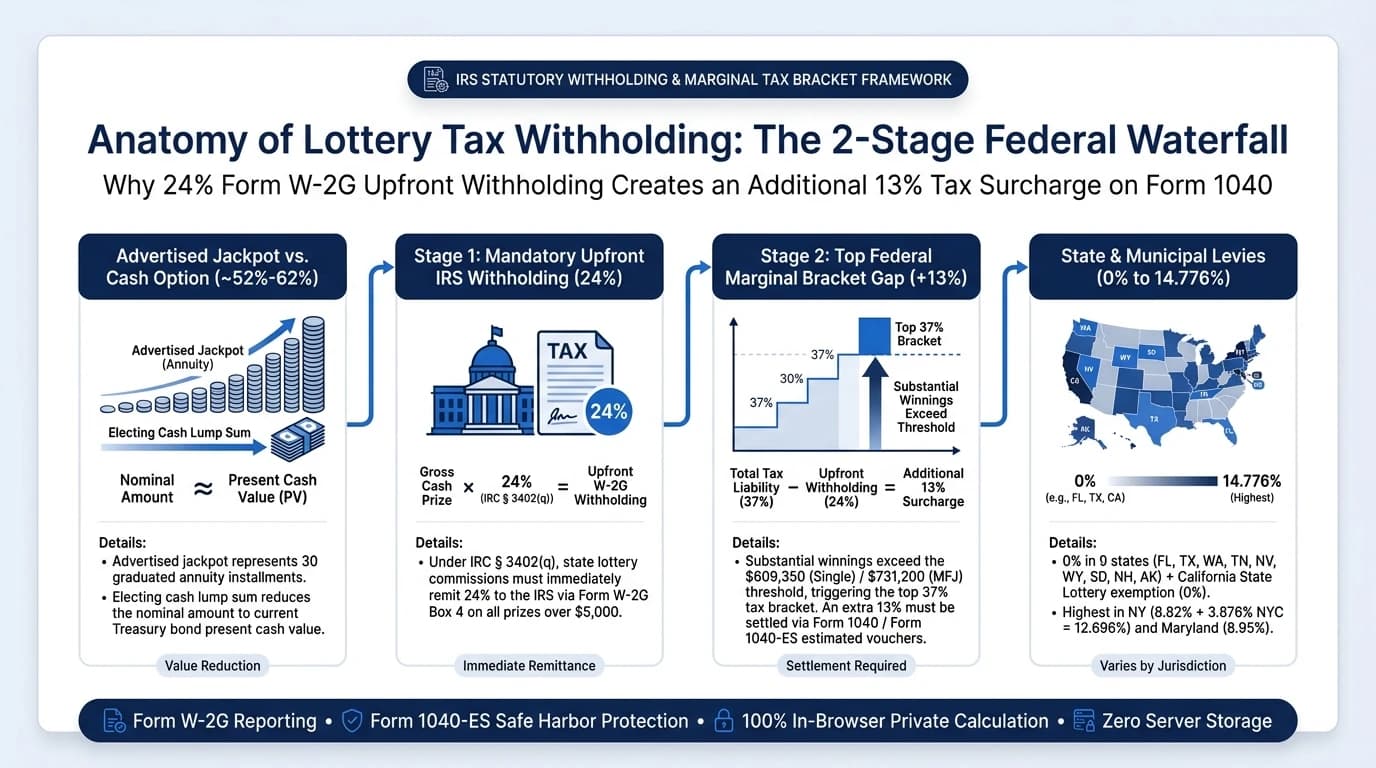
Under IRC § 3402(q)(3)(B), state lottery agencies automatically withhold a mandatory 24% upfront federal tax on state lottery prizes exceeding $5,000, reported on Form W-2G Box 4. At tax filing, lottery proceeds are reported on Schedule 1 (Form 1040) Line 8b as ordinary income. Any taxable income above $640,600 (Single) or $768,700 (MFJ) for 2026 triggers the top 37% federal bracket. State taxes range from 0% (in AK, FL, NV, NH, SD, TN, TX, WA, WY, and CA under Cal. Gov. Code § 8880.68) up to 10.90% in NY (plus 3.876% NYC and 16.75% of state tax in Yonkers).
Under IRC § 3402(q)(3)(B), state commissions deduct 24% on prizes >$5,000 via Form W-2G Box 4.
Income exceeding $640,600 (Single) triggers 37%. The remaining balance is reconciled on Form 1040.
In prevailing 4.5% Treasury yield environments, the cash option discounts to ~50.2% of nominal jackpot.
9 states have no personal income tax. California completely exempts in-state lottery prizes. NY reaches up to 10.90%.
2026 Prize Parameters & Tax Settings
Tax Year 2026 Statutory RatesMandatory 24% IRS withholding applies to prizes >$5,000 under IRC § 3402(q)(3)(B).
Anatomy of Lottery Tax Withholding: The 2-Stage Federal Waterfall
Why the 24% Form W-2G upfront withholding creates a tax shortfall when reconciling on Form 1040 in 2026.
Lump Sum vs. 30-Year Graduated Annuity: Comprehensive Comparative Audit
A definitive comparison between the present cash value election and the 30-installment graduated annuity (5% compounding annual step-up under MUSL rules).
| Comparative Dimension | Cash Lump Sum Option | 30-Year Graduated Annuity | Fiduciary & Tax Impact |
|---|---|---|---|
| Total Cash Disbursed | ~45% to 52% of advertised jackpot (market yields) | 100% of advertised nominal jackpot | Annuity pays full figure over 29 years via 5% compounding annual step-ups. |
| Year 1 Cash Liquidity | Immediate full payout upon claim verification | Approx. 1.505% of gross jackpot in payment #1 | Lump sum grants maximum liquidity for debt settlement, real estate, and trust funding. |
| Tax Bracket Risk | 1-time tax event at current 2026 statutory 37% bracket | 30 separate annual tax events subject to rate changes | Annuity exposes winner to future congressional tax legislation over a 3-decade horizon. |
| Inflation & Investment Yield | Zero erosion on principal if invested in diversified index funds | Partially hedged by 5% annual payout step-up | Historically, diversified equities (7%–10%) outperform Treasury bond discount rates. |
| Estate Tax (IRC § 2031) | Remaining liquid assets taxed under gross estate | Critical estate liquidity hazard upon death | Heirs must pay federal 40% estate tax within 9 months on the present value of future annuity installments. |
| Behavioral Bankruptcy Shield | Higher behavioral risk without disciplined wealth governance | Guaranteed annual financial reset for 30 years | Protects winners from predatory lending, fraudulent solicitations, and rapid capital exhaustion. |
Worked Example: $10 Million Jackpot in California vs. New York City (2026)
How IRC § 3402(q)(3)(B) withholding, Schedule 1 Form 1040 progressive tax reconciliation, and state-level statutory exemptions shape real take-home net proceeds for the 2026 tax year.
California Jurisdiction (0% State Tax on CA Lottery)
Cal. Gov. Code § 8880.68New York City Jurisdiction (Highest Combined Burden)
10.30% State + 3.876% NYCHow Much Do You Actually Win After Taxes? ($100k to $1.5 Billion)
Authoritative mathematical reconciliation across high-volume queries: “$1M after taxes”, “$5M lottery payout”, and “$10M lump sum take-home” under statutory 2026 progressive IRS rates (Single filer).
| Prize Category | Cash Gross Amount | Upfront 24% IRS Withholding | Total Statutory Federal Tax | Form 1040 Settlement Gap | Net: 0% Tax States (FL, TX, CA, WA, AK) | Net: NY State Winner |
|---|---|---|---|---|---|---|
| $100,000 (Instant Scratch-Off) | $100,000 (100% Cash) | -$24,000 | -$13,170 (Progressive) | +$10,830 (Refund) | $86,830 | $79,980 |
| $500,000 (Powerball Match 5) | $500,000 (100% Cash) | -$120,000 | -$138,134 (Progressive) | -$18,134 | $361,866 | $327,616 |
| $1,000,000 ($1 Million Cash) | $1,000,000 (100% Cash) | -$240,000 | -$320,000 (Progressive) | -$80,000 | $680,000 | $611,500 |
| $2,000,000 ($2 Million Cash) | $2,000,000 (100% Cash) | -$480,000 | -$690,000 (Progressive) | -$210,000 | $1,310,000 | $1,117,000 |
| $5,000,000 ($5 Million Jackpot) | $2,510,000 (~50.2% PV) | -$602,400 | -$878,700 (Progressive) | -$276,300 | $1,631,300 | $1,392,850 |
| $10,000,000 ($10 Million Jackpot) | $5,020,000 (~50.2% PV) | -$1,204,800 | -$1,807,400 (Progressive) | -$602,600 | $3,212,600 | $2,695,540 |
| $100,000,000 ($100 Million Jackpot) | $50,200,000 (~50.2% PV) | -$12,048,000 | -$18,524,000 (Progressive) | -$6,476,000 | $31,676,000 | $26,204,200 |
| $1,500,000,000 ($1.5 Billion Jackpot) | $753,000,000 (~50.2% PV) | -$180,720,000 | -$278,560,000 (Progressive) | -$97,840,000 | $474,440,000 | $392,363,000 |
50-State Lottery Tax Withholding & Statutory Exemption Table (2026)
State-by-state statutory withholding percentages, 2026 top individual marginal income tax rates, and special legislative exemptions.
| State Jurisdiction | Mandatory State Withholding | Top State Marginal Rate (2026) | Exemption & Statutory Notes |
|---|---|---|---|
| Alabama (AL)No State Lottery | 5.00% | 5.00% | Alabama does not operate a state lottery. Out-of-state winnings are taxed at Alabama's top 5.00% state income tax rate. |
| Alaska (AK)No State Lottery | 0.00% | 0.00% (0% State Tax) | Alaska levies no state personal income tax and does not operate a state lottery. 100% state tax-free. |
| Arizona (AZ) | 2.50% | 2.50% | Flat 2.50% state individual income tax rate. Arizona Lottery withholding is 2.50%, matching the flat tax rate. |
| Arkansas (AR) | 3.70% | 3.70% | 3.70% top individual income tax rate enacted under 2026 state tax reform. |
| California (CA) | 0.00% | 0.00% (0% State Tax) | Under Cal. Gov. Code § 8880.68 (Proposition 37), California State Lottery winnings are 100% exempt from CA state income tax. Non-lottery prizes (game shows/sweepstakes) taxed up to 13.3%. |
| Colorado (CO) | 4.40% | 4.40% | Statutory 4.40% flat individual income tax rate applies to all proceeds. |
| Connecticut (CT) | 6.99% | 6.99% | Top state rate of 6.99% on income over $500,000; mandatory 6.99% Connecticut Lottery withholding. |
| Delaware (DE) | 0.00% | 6.60% | Delaware Lottery does not withhold state tax at source (0.00% withholding). Winnings are taxed on Form PIT-RES up to 6.60% (permits anonymous trust claiming). |
| District of Columbia (DC) | 8.50% | 10.75% | 8.50% mandatory withholding on prizes >$5,000; top marginal rate is 10.75% for income exceeding $1,000,000. |
| Florida (FL) | 0.00% | 0.00% (0% State Tax) | Constitutional 0% personal income tax. Only federal taxes apply to Florida lottery winnings. |
| Georgia (GA) | 4.99% | 4.99% | Flat 4.99% uniform state income tax rate for 2026 under HB 463. |
| Hawaii (HI)No State Lottery | 0.00% | 11.00% | Hawaii does not operate a state lottery. Out-of-state lottery winnings are taxed up to Hawaii's 11.00% top marginal rate. |
| Idaho (ID) | 5.30% | 5.30% | Flat 5.30% state individual income tax rate under HB 40 for 2026. |
| Illinois (IL) | 4.95% | 4.95% | Flat 4.95% state personal income tax rate on prize winnings exceeding $1,000. |
| Indiana (IN) | 2.95% | 2.95% | Flat 2.95% state income tax rate for 2026. County taxes (up to ~3.0%) may also apply. |
| Iowa (IA) | 3.80% | 3.80% | Flat 3.80% income tax rate under SF 2442. Iowa Lottery withholding is 3.80%. |
| Kansas (KS) | 5.00% | 5.58% | Top marginal rate is 5.58% under SB 1. Mandatory 5.00% state withholding on prizes >$5,000 (permits anonymous trust claiming). |
| Kentucky (KY) | 3.50% | 3.50% | Flat 3.50% state individual income tax rate effective for 2026. |
| Louisiana (LA) | 0.00% | 3.00% | Flat 3.00% individual income tax rate. Louisiana Lottery has 0.00% mandatory state withholding at payout. |
| Maine (ME) | 5.00% | 7.15% | 7.15% top marginal income tax rate; Maine Lottery withholds 5.00% upfront on prizes >$5,000. |
| Maryland (MD) | 8.95% | 8.95% | 8.95% withholding for MD residents (5.75% state + 3.20% county piggyback); 8.00% for nonresidents. Permits anonymous claiming. |
| Massachusetts (MA) | 5.00% | 9.00% | 5.00% base rate + 4.00% Fair Share Amendment surtax on income over $1,000,000 (= 9.00%). Upfront withholding is 5.00%. |
| Michigan (MI) | 4.25% | 4.25% | Flat 4.25% state personal income tax rate. |
| Minnesota (MN) | 7.25% | 9.85% | 9.85% top marginal rate on income over $193,000; Minnesota Lottery withholds 7.25% on prizes >$5,000. |
| Mississippi (MS) | 3.00% | 4.00% | Flat 4.00% rate in 2026 under Build-Up MS Act. Mandatory state lottery withholding is 3.00% on prizes $600+ (allows anonymous claiming). |
| Missouri (MO) | 4.00% | 4.70% | 4.70% top individual income tax rate; Missouri Lottery withholds 4.00% upfront on prizes >$600. |
| Montana (MT) | 5.65% | 5.65% | 5.65% top marginal rate for 2026 under HB 337. Allows anonymous entity claiming. |
| Nebraska (NE) | 3.50% | 4.55% | Top state rate is 4.55% for 2026 under LB 754. Nebraska Lottery withholds 3.50%. |
| Nevada (NV)No State Lottery | 0.00% | 0.00% (0% State Tax) | No state income tax. Nevada does not operate a state lottery, but out-of-state winnings are 0% state taxed. |
| New Hampshire (NH) | 0.00% | 0.00% (0% State Tax) | 0.00% state tax on earned income and lottery payouts. |
| New Jersey (NJ) | 8.00% | 10.75% | 10.75% top rate on income over $1,000,000 (8.97% between $500k and $1M). Mandatory 8.00% withholding on prizes >$500,000 (5.00% on $10k–$500k; anonymous claiming permitted). |
| New Mexico (NM) | 6.00% | 5.90% | 5.90% top individual rate under HB 252; New Mexico Lottery statutorily withholds 6.00% on prizes >$5,000. |
| New York (NY) | 10.90% | 10.90% | 10.90% top state rate on income >$25M (10.30% on $5M–$25M; mandatory 10.90% withholding on major prizes). NYC residents add +3.876% city tax. Yonkers adds 16.75% of state tax liability. |
| North Carolina (NC) | 3.99% | 3.99% | Flat 3.99% state rate for 2026 under scheduled tax reform. |
| North Dakota (ND) | 2.50% | 2.50% | 2.50% top rate under HB 1158 (first $44,725 is 0%). Mandatory 2.50% withholding on prizes >$5,000 (permits anonymous trust claiming). |
| Ohio (OH) | 2.75% | 2.75% | 2.75% top rate on income over $26,050 under HB 33/HB 96 (0% on first $26,050); Ohio Lottery withholds 2.75% upfront for 2026 under ORC § 5747.062 (anonymous claiming permitted). |
| Oklahoma (OK) | 4.00% | 4.50% | Top marginal rate is 4.50% for 2026 under HB 2764. 4.00% mandatory withholding. |
| Oregon (OR) | 8.00% | 9.90% | 9.90% top rate on income over $125,000; Oregon Lottery withholds 8.00% upfront on prizes $1,500+. |
| Pennsylvania (PA) | 3.07% | 3.07% | Flat 3.07% PA personal income tax under Act 84 of 2016 (72 P.S. § 7303(a)(7)). PA Lottery withholds 3.07% on cash prizes >$5,000. Noncash prizes remain exempt. |
| Rhode Island (RI) | 5.99% | 5.99% | 5.99% top marginal income tax and withholding rate on earnings over $178,000. |
| South Carolina (SC) | 5.21% | 5.21% | Top individual income tax rate is 5.21% for 2026 under phased tax relief (permits anonymous claiming). |
| South Dakota (SD) | 0.00% | 0.00% (0% State Tax) | No state personal income tax. 100% state tax-free. |
| Tennessee (TN) | 0.00% | 0.00% (0% State Tax) | 0% state income tax on all earnings and lottery winnings. |
| Texas (TX) | 0.00% | 0.00% (0% State Tax) | Constitutional 0% personal income tax (TX Const. Art. VIII § 24-a). |
| Utah (UT)No State Lottery | 4.45% | 4.45% | Utah does not operate a state lottery. Out-of-state winnings taxed at flat 4.45% for 2026 under SB 60. |
| Vermont (VT) | 6.00% | 8.75% | 8.75% top personal rate; Vermont Lottery withholds 6.00% on prizes >$5,000. |
| Virginia (VA) | 4.00% | 5.75% | 5.75% top rate on income over $17,000; Virginia Lottery withholds 4.00% on prizes >$5,000. |
| Washington (WA) | 0.00% | 0.00% (0% State Tax) | No personal income tax. Lottery winnings are 100% state tax-free. |
| West Virginia (WV) | 4.58% | 4.58% | Top rate is 4.58% for 2026 under SB 392. |
| Wisconsin (WI) | 7.65% | 7.65% | 7.65% top state personal income tax rate on earnings over $304,000. |
| Wyoming (WY) | 0.00% | 0.00% (0% State Tax) | No state personal income tax (permits anonymous trust/LLC claiming). |
| Puerto Rico (PR) | 20.00% | 20.00% | Special territorial sliding scale withholding up to 20.00% under 15 L.P.R.A. § 811. |
Sweepstakes, Game Show Winnings & Non-Cash Prize Taxation (IRC § 74)
Taxes on cars, vacation packages, and television game show prizes (The Price is Right, Jeopardy!, Wheel of Fortune) operate under strict non-withholding rules in 2026.
Fair Market Value (FMV) Rule
Under 26 U.S. Code § 74, non-cash prizes (like cars, boats, or electronics) are taxed on their retail Fair Market Value, reported via Form 1099-MISC Box 3. You cannot pay taxes using a portion of the vehicle; you must remit cash out-of-pocket to the IRS.
The Vacation Forfeiture Trap
Trips won on TV game shows are taxed at the show's stated travel package retail value. Many winners forfeit trips before accepting them because the accompanying federal and state tax burden often exceeds what booking the flight independently would cost.
California Sourcing Rule
Contestants from other states who win on game shows filmed in California (e.g. Jeopardy! in Culver City or The Price is Right) owe California nonresident income tax up to 13.3% on those specific earnings, regardless of home state residency, because game show winnings are not exempt under California Government Code § 8880.68.
What to Do in the First 72 Hours: Institutional Advisory Protocol
Actionable steps recommended by estate tax attorneys, CPAs, and fiduciary financial planners prior to claiming an eight- or nine-figure jackpot.
Secure Ticket & Establish Custody
Sign the back of the winning ticket immediately. A lottery ticket is a bearer instrument; whoever holds it can claim it. Store the physical slip in a bank safe deposit box or commercial vault.
Assemble the Fiduciary Triad
Retain an experienced Tax Attorney (specializing in estate and trust governance), a Partner-Level CPA for estimated quarterly payments, and a Fee-Only CFP. Avoid commission-based wealth managers.
Evaluate Trust & Entity Claiming
Determine if your state permits anonymous claiming through a Blind Trust or LLC (permitted in DE, KS, MD, MS, MT, NJ, ND, OH, SC, WY). Once your personal identity is made public, privacy cannot be restored.
The Critical Gift Tax Pitfall (IRC § 2501 & § 2503(b))
Do not verbally promise or transfer fractions of a winning ticket to relatives before signing a formal co-ownership agreement. Claiming the prize individually and then distributing multi-million dollar portions triggers the 40% Federal Gift Tax on transfers exceeding the annual $19,000 exclusion and lifetime unified credit ($15.00M in 2026 under the One Big Beautiful Bill Act). Always execute an official lottery pool co-ownership agreement prior to validation.
Frequently Asked Questions: Lottery Tax Rules & Withholding (2026)
Direct, regulatory-grounded answers to top questions asked by lottery winners, attorneys, and compliance officers for the 2026 tax year.
Under 26 U.S. Code § 3402(q)(3)(B), state lottery agencies mandate an immediate 24% upfront federal withholding on all state lottery prizes exceeding $5,000, documented on Form W-2G Box 4. In addition, state lottery commissions withhold mandatory 2026 state taxes (ranging from 0% in California, Florida, and Texas up to 10.90% in New York and 8.95% in Maryland; Pennsylvania withholds flat 3.07% on cash prizes over $5,000 under Act 84 of 2016). The 24% upfront withholding is an estimated deposit toward your tax liability, not your final tax bill.
Related Tax Compliance & Verification Workflows
Complete official Rev. March 2024 Form W-9 for prize disbursements, banking escrow, and vendor verification.
Detailed 2026 ordinary income tax brackets (10%–37%) across Single, MFJ, HOH, and MFS.
Calculate statutory FICA (Social Security & Medicare) withholding alongside state and local levies.
Model Form 2210 underpayment interest and failure-to-pay penalties under IRC § 6651 & § 6654.
Statutory 2026 Tax Year Waterfall • IRC § 3402(q)(3)(B) & § 1 Reconciliation
| Line Item Description | Statutory Reference | Calculated Amount |
|---|---|---|
| Gross Taxable Payout Amount | Cash Present Value (~50.2% PV) | $50,200,000 |
| Mandatory Upfront IRS Withholding | 24% Statutorily Remitted via Form W-2G Box 4 | -$12,048,000 |
| Mandatory Upfront State Withholding | California (0.00%) | -$0 |
| Initial Check Disbursed (Payout Day) | Gross proceeds minus upfront statutory withholdings | $38,152,000 |
| Federal Tax Shortfall Balance Due | Reconciled on Form 1040 (Schedule 1 Line 8b) | -$6,476,000 |
| Total Progressive Federal Income Tax | IRC § 1 Marginal Rates (10% to 37%) | -$18,524,000 |
| State Personal Income Tax | California (0.00%) • Cal. Gov. Code § 8880.68 | $0.00 (Exempt) |
| FINAL TRUE NET CASH TAKE-HOME | $31,676,000 | |