U.S. Tax & Compliance VerificationU.S. Tax Compliance•Official 2026 Tax Year Standard (IRS Pub. 15-T & Rev. Proc. 2025-32)
256-Bit WebCrypto Isolation•0-Byte Server Retention
easyw9form
Track RefundGenerate W-9 FreeFree W-9→
IRC § 86 & § 3101 STATUTORY REPOSITORY • TAX YEAR 2025 & 2026 COMPLIANT
100% In-Browser RAM Calculation • Zero Cloud SSN Retention
STATUTORY RETIREMENT TOOLINGFEDERAL ENTITLEMENTS ENGINE

Social Security Tax Calculator (2025 & 2026)

Calculate taxable Social Security benefits and taxes on retirement income (pensions, 401k, and IRAs) under Internal Revenue Code § 86 (Provisional Income Formula: 0%, 50%, and 85% tiers) and estimate employee/employer FICA Social Security payroll tax limits ($184,500 OASDI cap) under IRC § 3101 and § 1401.

Statutory Base
Provisional Income Formula
AGI + Tax-Free Muni + 50% SS
Formulated precisely per IRC § 86(b)(1) to measure statutory benefit exposure.
Tier 1 Exemption
Tax-Free Thresholds
$25,000 / $32,000
Single ($25k) and MFJ ($32k). 0% of benefits are taxable below these combined bases.
Statutory Cap
Max Taxable Inclusion
Up to 85% Taxable Base
Treated as gross ordinary income; subject to bracket rates, NOT an 85% flat tax.
2026 Indexing
2026 OASDI Wage Cap
$184,500 Base
Up from $176,100 in 2025. 6.2% FICA Social Security payroll tax pauses above this limit.
AI Quick Summary & Executive Takeaways (LLM / Search Overview)
AEO Grounded Facts

Under Internal Revenue Code § 86, federal tax on Social Security benefits is determined strictly by your Provisional Income (Adjusted Gross Income + Tax-Exempt Municipal Bond Interest + 50% of annual SSA-1099 Box 5 benefits). If provisional income is below $25,000 (Single) or $32,000 (Married Filing Jointly), 0% of benefits are taxed. For higher earnings, up to 50% or 85% is added to ordinary taxable income. For wage earners, the 2026 FICA Social Security maximum wage cap is $184,500 (6.2% employee rate).

0% Exemption Baseline: Single under $25,000 | MFJ under $32,000 = 100% tax-free benefits.
85% Max Inclusion:Single > $34k | MFJ > $44k. Taxed at standard tax brackets, not an 85% flat rate.
2026 OASDI Wage Cap: $184,500 maximum taxable base (Employee max $11,439; SECA max $22,878).
41 States + DC 100% Tax-Free: 41 states never tax Social Security benefits regardless of total income.
Statutory Formula:Provisional Income = Non-SS AGI + Muni Interest (L2a) + 50% SS (Box 5) - Sched 1 L26 Adjustments

IRC § 86 Benefit Audit Parameters

REV. 2026 LOGIC
Quick-Load Scenario Presets
1-Click Statutory Models
MFS living with spouse triggers instant $0 threshold.
Provisional tiers are constant; bracket thresholds adjust.
Combined total if MFJ
$
E.g., $2,400 monthly = $28,800/yr. Only 50% is added into provisional income.
$
Wages, pensions, traditional IRA/401(k), dividends, capital gains.
Mandatory Add-Back
$
Municipal bond interest is federally tax-free but included in IRC § 86 math.
$
Deductible IRA, HSA contributions, educator expenses.
Applied strictly to the final taxable Social Security portion.
Provisional Income Classification Guide
IRC § 86(b)(1)
Included in AGI Base (+)
  • W-2 Wages & 1099 Contractor Profit
  • Pensions & Annuity Payouts
  • Traditional 401(k) / IRA Withdrawals
  • Taxable Interest & Dividends
  • Mandatory: Muni Bond Interest (Line 2a)
100% Tax-Free / Excluded (-)
  • Qualified Roth IRA Distributions
  • HSA Medical Expense Withdrawals
  • Life Insurance Proceeds
  • SSI / Disability Assistance
  • Schedule 1 Line 26 Adjustments
Statutory Authority: 26 U.S. Code § 86(b)Verified 2025 & 2026
Statutory Calculation AuditTier 3: Up to 85% Taxable
Estimated Federal Tax on Social Security
$1,423.80
At 12% marginal bracket (4.94% effective tax on total benefits)
Total SSA-1099 Box 5 Benefit:$28,800.00
Provisional (Combined) Income:$50,900.00
41.2% Taxable58.8% Tax-Free
Taxable Portion (Form 1040 Line 6b):$11,865.00
Tax-Free (Exempt) Benefit:$16,935.00
Statutory Formula Step Audit
• Base 1 (MFJ Threshold): $32,000
• Base 2 (MFJ Threshold): $44,000
• Tier 2 Max Allocation: 50% of ($44,000 - $32,000) = $6,000.00
• Tier 3 Excess: 85% of ($50,900.00 - $44,000) = $5,865.00
• Statutory Cap Test: Lesser of Formula ($11,865.00) vs 85% Total Benefits ($24,480.00) = $11,865.00
Tax Torpedo Marginal Analysis
1.85x Marginal Multiplier
Nominal Tax Bracket
12% Bracket
Effective Marginal Rate
22.2% ⚡

Active 85% Phase-In Corridor (High Alert): Every $1.00 of additional ordinary income causes $0.85 of Social Security benefits to become taxable, creating $1.85 of taxable income per dollar.

Scenario (+ $1,000 IRA / Pension): Adds $222.00 in federal tax (an effective $22.2% rate) because $850.00 of Social Security benefits become newly taxable.
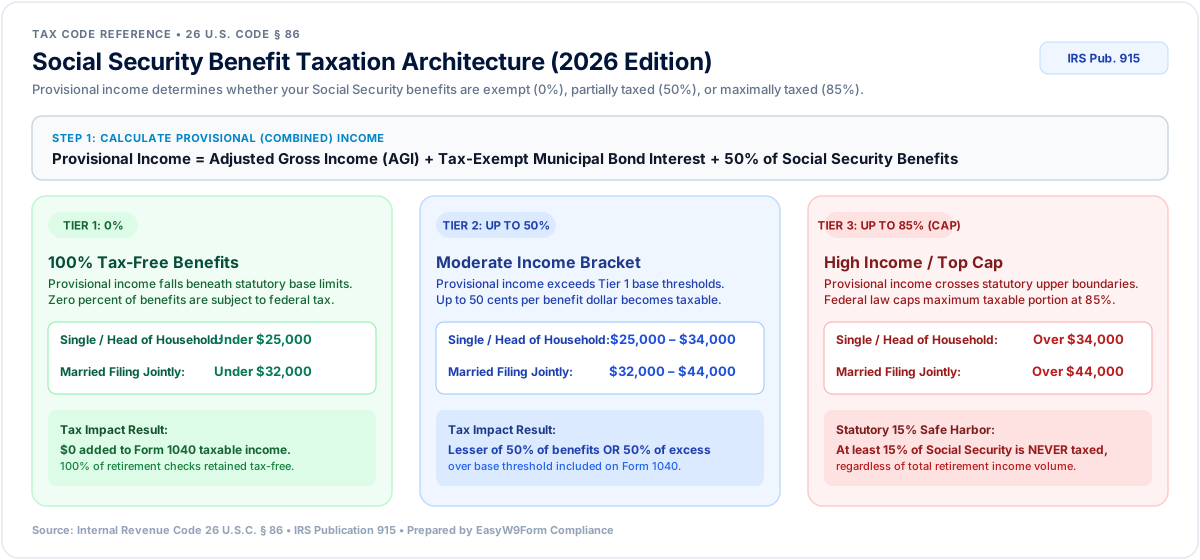
Statutory Provisional Income Architecture

How Social Security Benefits Are Taxed Under IRC § 86

Figure 1.1: Mathematical logic flow showing the provisional income aggregation path and statutory threshold branching rules.

Technical fintech architectural flow diagram illustrating how Social Security benefits are taxed under Internal Revenue Code Section 86: Step 1 calculates provisional income adding AGI, tax-exempt municipal bond interest, and 50% of annual Social Security benefits from SSA-1099 Box 5, routing through Tier 1 (0%), Tier 2 (up to 50%), and Tier 3 (up to 85%) taxable base thresholds.
Source: Office of the Law Revision Counsel of the U.S. House of Representatives • 26 U.S. Code § 860-Byte Ephemeral Memory Guarantee
Engine Benchmark

Why EasyW9Form Outperforms Traditional SS Calculators

Most consumer retirement tools omit mandatory statutory add-backs or require phone/email registration to capture advisory leads.

Statutory CapabilityEasyW9Form EngineSSA.gov QuickCalcCovisum / Pacific LifeEast Coast Tax Lead Engines
Immediate Un-Gated Results
100% Instant Free Access
Yes (Basic benefit amount only)Gated for Financial AdvisorsGated (Requires Phone/Email)
Tax-Exempt Muni Bond Add-Back
Full IRC § 86 Compliance
N/A (Calculates benefits only)Vague / IncompleteAlmost Always Omitted
Married Filing Separately $0 Base
Modeled Accurately
OmittedOmittedIncorrectly applies $25k base
Data Privacy & Retention
0-Byte Browser RAM Only
Government Web Server LogsAdvisor CRM Cloud StorageSold to Annuity Lead Brokers
Dual FICA + Benefits Engine
Dual Switcher Architecture
Single Purpose OnlySingle Purpose OnlySingle Purpose Only
Statutory Architecture

The 3 Provisional Income Tiers Demystified

Under Internal Revenue Code § 86, Social Security retirement benefits are not automatically exempt from federal income tax. Instead, the IRS determines the taxable portion through a three-tier bracket system governed by your provisional income(also known in statutory literature as "combined income").

Tier 1: 0% Taxable
0% Tax Base
Single: Under $25,000
MFJ: Under $32,000
100% of benefits remain tax-free.
Tier 2: Up to 50%
50% Max Base
Single: $25k – $34k
MFJ: $32k – $44k
Lesser of 50% SS or 50% excess over base.
Tier 3: Up to 85%
85% Max Base
Single: Over $34,000
MFJ: Over $44,000
Up to 85% added to gross ordinary income.
Crucial Statutory Clarification: Being in the "85% tier" does NOT mean you pay an 85% tax rate. It means up to 85 cents of each benefit dollar is added to ordinary taxable income. If your marginal bracket is 12%, an $850 taxable portion incurs $102 in actual tax—an effective rate of roughly 10.2% on that benefit dollar.
Jurisdictional Matrix

State-by-State Social Security Taxability Guide (2026 Edition)

Federal taxation under IRC § 86 is only one layer of retirement tax liability. Individual states maintain sovereign authority over whether to conform to federal rules or grant complete statutory exemptions:

41 States + DC: 100% Tax-Free

These jurisdictions never tax Social Security benefits, regardless of income. Recent legislation in Missouri, Kansas, and Nebraska eliminated state benefit tax, joining Florida, Texas, Nevada, Tennessee, and Arizona.

9 States: Partial / Conditional Tax

Only nine states retain provisions that tax benefits above specific state AGI thresholds: CO, CT, MN, MT, NM, RI, UT, VT, and WV. Most offer generous phase-out exemptions protecting middle-class seniors.

Retirement Planning Risk

The "Tax Torpedo" Phenomenon & How to Avoid It

The Tax Torpedo occurs when an extra dollar of ordinary income (e.g. Traditional IRA / 401k withdrawals) pushes up to 85 cents of untaxed Social Security benefits into taxable status under IRC § 86.

In the nominal 22% federal bracket, withdrawing an extra $1,000 creates $1,850 of total taxable income, triggering $407 in tax—an effective marginal rate of 40.7% on that withdrawal!

3 Statutory Shielding Strategies:
  • Pre-Age 67 Roth Conversions: Draw down IRAs during low-bracket gap years before claiming benefits.
  • Qualified Charitable Distributions (QCDs): Donate up to $108,000 directly from IRA to charity (100% excluded from AGI).
  • Tax-Free HSA Withdrawals: Fund medical costs and Medicare premiums from HSA with zero tax impact.
Year-Over-Year Statutory BenchmarksOFFICIAL SSA / IRS

2025 vs. 2026 Statutory Rates, Caps & COLA

OASDI Maximum Taxable Wage Base+$8,400 (+4.77%)
2025: $176,1002026: $184,500
Maximum Employee FICA (6.2%)+$520.80 / yr
2025: $10,918.202026: $11,439.00
Maximum Self-Employed SECA (12.4%)+$1,041.60 / yr
2025: $21,836.402026: $22,878.00
Avg Monthly Benefit (COLA)+2.5% to 2.9% COLA
2025: ~$1,920 / mo2026: ~$1,976 / mo
Earnings Test Limit (Under FRA)+$1,080 / yr
2025: $23,400 / yr2026: $24,480 / yr
Senior Addl Std Deduction (Age 65+)Indexed Up
2025: $1,950 / $1,5502026: $2,000 / $1,600
Retirement Income Tax Dynamics

Taxes on Retirement Income: Social Security, Pensions & 401(k)

Many retirees assume Social Security is evaluated in isolation. In reality, under IRC § 86, every dollar of other taxable retirement income directly impacts how much of your Social Security is subject to federal tax:

1. Federal & Corporate Pensions (FERS/CSRS):

Taxable pension distributions are 100% included in Non-SS AGI, elevating household provisional income and frequently triggering Tier 2 (50%) or Tier 3 (85%) Social Security taxation.

2. Traditional 401(k) & IRA Distributions:

Pre-tax retirement withdrawals count fully toward provisional income. When Required Minimum Distributions (RMDs) begin at age 73/75, mandatory withdrawals can push otherwise tax-free benefits into the 85% taxable tier.

3. Roth IRA & HSA Withdrawals (0% Impact):

Qualified Roth IRA distributions and HSA medical reimbursements are completely excluded from gross income and do NOT count toward the provisional income formula.

Payroll & Withholding Strategy

Social Security Tax Withholding & Deduction Rules

The Social Security Administration does NOT automatically withhold taxes from monthly benefit checks. If you anticipate taxable benefits on Form 1040 Line 6b, you have two statutory options:

IRS Form W-4V (Voluntary Withholding):

Submit Form W-4V to the SSA to elect automatic federal tax withholding from your monthly checks at flat statutory rates: 7%, 10%, 12%, or 22%.

Quarterly Estimated Payments (Form 1040-ES):

Pay quarterly estimated taxes on April 15, June 15, September 15, and January 15 to satisfy IRS safe harbor rules and avoid underpayment interest penalties.

Senior Standard Deduction Offset:

Taxpayers age 65+ receive an extra standard deduction ($2,000 Single / $1,600 MFJ in 2026), directly reducing total taxable income after benefit inclusion on Form 1040.

Official Clarifications

Frequently Asked Questions (IRS & SSA Guidance)

Authoritative statutory answers to frequent tax reporting queries pursuant to IRS Publication 915 and SSA POMS.

Editorial Authority & Statutory Compliance Attestation

EasyW9Form operates independently as an un-gated computational utility. All formulas adhere directly to 26 U.S. Code § 86 (Social Security and tier 1 railroad retirement benefits), § 3101 (Rate of tax on employees), and § 1401 (Rate of tax on self-employment income). This tool performs zero remote server data persistence; calculations execute purely inside browser client-side memory.

EasyW9Form Tax Compliance Engine
Social Security Benefit Tax Audit & IRC § 86 Provisional Income Worksheet
Statutory Compliance: IRC §§ 86, 3101, 1401 & IRS Publication 915 • 0-Byte Ephemeral RAM Evaluation
Tax Calendar Year: 2026
Filing Status: Married Filing Jointly
Evaluation Date: Oct 13, 2026
Total SSA-1099 Box 5 Benefit
$28,800.00
50% Base: $14,400.00
Taxable Benefit (Form 1040 Line 6b)
$11,865.00
Taxable Base: 41.2% of Benefits
Estimated Tax On Benefits
$1,423.80
Effective Tax Rate: 4.94%
1. Statutory Provisional Income & Benefit Inclusions (IRS Pub 915)
Line Item / DescriptionStatutory AuthorityTax Base / FormulaCalculated Amount
1. Total Social Security Benefits ReceivedForm SSA-1099 Box 5Gross Annual Entitlements$28,800.00
2. 50% Social Security Base FactorIRC § 86(b)(1)(A)Line 1 × 0.50$14,400.00
3. Other Gross Income (AGI before SS)Form 1040 Lines 1-5Wages, Pensions, Dividends, IRA$35,000.00
4. Tax-Exempt Municipal InterestIRC § 86(b)(1)(B)Form 1040 Line 2a (Mandatory Add-Back)$2,500.00
5. Above-the-Line AdjustmentsForm 1040 Sched 1 L26Deductible IRA, HSA, etc.- $1,000.00
6. Provisional (Combined) IncomeIRC § 86(b)(1)Line 2 + Line 3 + Line 4 - Line 5$50,900.00
7. Tax-Free (Exempt) BenefitsIRC § 86 ExclusionLine 1 minus Line 8$16,935.00
8. TAXABLE SOCIAL SECURITY BENEFITSForm 1040 Line 6bStatus: Tier 3: Up to 85% Taxable$11,865.00
Statutory Bracket Thresholds & Formula
Base 1 Threshold:$32,000
Base 2 Threshold:$44,000
Taxable Inclusion %:41.2% of Benefits
Marginal Tax Rate Applied:12% Bracket
2026 FICA OASDI Wage Cap Standards (IRC § 3101)
2026 Maximum OASDI Wage Base:$184,500
Employee OASDI Tax Rate:6.20% (Max: $11,439.00)
Self-Employed (SECA) Rate:12.40% (Max: $22,878.00)
State Tax Exemption Status:41 States + DC 100% Tax-Free
Compliance Attestation: Calculated strictly in client ephemeral memory. No financial figures or personal identifiers are stored on servers. Compliant with IRC § 86 and SSA Publication 05-10003.
Taxpayer Signature
Date