Official Estimated Tax Liability Statement (Form 1040 & State Tax Return Synchronized)
Illinois Paycheck Calculator (2026 Take-Home Pay)
Calculate your exact net take-home salary after Federal Income Tax (FIT), FICA OASDI (6.2%), Medicare (1.45%), Additional Medicare (0.9%), State, and local municipal withholdings. Real-time client-side calculation with zero lead gates and 2026 statutory limits.
Paycheck Parameters
Adjust salary, frequency, filing status, and deductions.
Computes your true statutory income tax obligation by deducting the full standard deduction ($16,100 Single / $32,200 MFJ) upfront from annual gross pay before applying progressive tax brackets (identical to SmartAsset & Form 1040).
Illinois levies a constitutionally protected flat 4.95% tax rate with personal exemption allowances ($2,925 Single / $5,850 MFJ in 2026; phased out for incomes above $250k single / $500k married under 35 ILCS 5/204). Under 820 ILCS 105/, statewide minimum wage is $15.00/hr ($9.00 tipped cash; Chicago $16.60/hr). The Paid Leave for All Workers Act (PLAWA) mandates 40 hours of paid leave, 100% employer-funded. Local city income taxes are 0.00% statewide, and employee SDI/SUTA deductions are $0.00.
savingsPre-Tax Deductions (401k, Health, HSA / FSA)expand_more
tuneIRS Form W-4 Adjustments (Step 2c, Step 3 & Step 4c)expand_more
| Gross Earnings | $3,269.23 |
| Federal Income Tax (FIT) | -$379.62 |
| Social Security (6.2%) | -$202.69 |
| Medicare (1.45%) | -$47.40 |
| State Income Tax (IL) | -$156.26 |
| Net Direct Deposit | $2,483.26 |
Live Step-by-Step Statutory Tax Audit & Mathematical Breakdown
See exactly how your $3,269.23 ($85,000.00/yr) gross pay converts to $2,483.26 take-home pay. Below is the unredacted, live mathematical calculation showing federal tax brackets, Illinois state deductions, and FICA mandates.
Key Takeaways & Take-Home Pay Insights
Effective Tax Rate Breakdown
On an $85,000 gross salary, estimated net take-home pay is approximately 76.0% (~$2,483.26 bi-weekly) after standard federal income tax, baseline state tax, and mandatory FICA contributions.
FICA OASDI Cap Threshold
The 6.2% Social Security tax ceases once cumulative wages reach $184,500 in 2026, delivering an automatic late-year take-home pay boost to high-earning professionals.
Pre-Tax Shelter Optimization
Contributing $100 to a traditional 401(k) or HSA typically reduces take-home net pay by only ~$70 to $78 while shielding taxable earnings from federal (and state, where applicable) income tax brackets, creating instant 22%–28%+ statutory tax leverage.
Form W-4 Precision
The redesigned post-2020 IRS Form W-4 eliminated personal allowances; claiming Step 3 dependent credits ($2,200 per child for 2026 under OBBBA) immediately reduces annual federal withholding dollar-for-dollar on every paycheck.
Illinois Paycheck Calculation & Tax Withholding Guide (2026)
Illinois levies a constitutionally protected flat individual income tax rate of 4.95% under 35 ILCS 5/201. Instead of a standard deduction, Illinois provides personal exemption allowances ($2,925 single / $5,850 married). Combined with a $15.00/hr statewide wage floor ($16.60 in Chicago), 0% municipal income taxes, and PLAWA paid leave protections, here is how Illinois take-home pay is determined:
Under 35 ILCS 5/201 & IL Const. Art. IX, Sec. 3, all taxable wages are taxed at a single flat 4.95% rate.
Basic personal exemption is $2,925 ($5,850 MFJ); phases out to $0 for AGI over $250k single / $500k married.
State minimum wage is $15.00/hr ($9.00 tipped cash); City of Chicago mandates $16.60/hr indexed to CPI.
Municipal income taxes are prohibited statewide; Chicago, Aurora, Joliet, and Rockford all levy 0.00%.
820 ILCS 192/ guarantees 40 hours of paid leave, 100% employer-funded. Employee SDI/SUTA deduction is $0.00.
Illinois Salary Paycheck Benchmarks (2026 Tax Year)
Estimated take-home calculations for a single employee claiming 1 personal exemption allowance ($2,925) with zero pre-tax deductions (incorporating the 4.95% flat tax and IRS Pub. 15-T withholding):
| Gross Salary | Fed Income Tax | FICA (7.65%) | IL State (4.95%) | Net Take-Home | Monthly Pay | Bi-Weekly | Effective Tax |
|---|---|---|---|---|---|---|---|
| $30,000 | $1,420 | $2,295 | $1,340 | $24,945 | $2,079 | $959 | 16.9% |
| $45,000 | $3,220 | $3,443 | $2,083 | $36,254 | $3,021 | $1,394 | 19.4% |
| $60,000 | $5,020 | $4,590 | $2,825 | $47,565 | $3,964 | $1,829 | 20.7% |
| $75,000 | $7,670 | $5,738 | $3,568 | $58,024 | $4,835 | $2,232 | 22.6% |
| $85,000 | $9,870 | $6,503 | $4,063 | $64,564 | $5,380 | $2,483 | 24% |
| $100,000 | $13,170 | $7,650 | $4,805 | $74,375 | $6,198 | $2,861 | 25.6% |
| $125,000 | $18,734 | $9,563 | $6,043 | $90,660 | $7,555 | $3,487 | 27.5% |
| $150,000 | $24,734 | $11,475 | $7,280 | $106,511 | $8,876 | $4,097 | 29% |
| $200,000 | $36,734 | $14,339 | $9,755 | $139,172 | $11,598 | $5,353 | 30.4% |
| $250,000 | $51,304 | $15,514 | $12,230 | $170,952 | $14,246 | $6,575 | 31.6% |
Illinois Hourly Paycheck Benchmarks (40 Hours / Week • 2,080 Hours / Year)
Take-home breakdown starting from Illinois' $15.00/hr statutory wage floor and Chicago's $16.60/hr rate up to $75.00/hr for non-exempt hourly employees:
| Hourly Rate | Benchmark Tier | Annual Gross | Federal Tax | FICA (7.65%) | IL State (4.95%) | Weekly Net | Bi-Weekly Net | Annual Take-Home |
|---|---|---|---|---|---|---|---|---|
| $15.00/hr | State Minimum Wage | $31,200 | $1,564 | $2,387 | $1,400 | $497 | $994 | $25,849 |
| $16.60/hr | City of Chicago Minimum | $34,528 | $1,963 | $2,641 | $1,564 | $545 | $1,091 | $28,360 |
| $20.00/hr | Entry Skilled | $41,600 | $2,812 | $3,182 | $1,914 | $648 | $1,296 | $33,692 |
| $25.00/hr | Mid-Level Professional | $52,000 | $4,060 | $3,978 | $2,429 | $799 | $1,597 | $41,533 |
| $30.00/hr | Senior Technical | $62,400 | $5,308 | $4,774 | $2,944 | $950 | $1,899 | $49,374 |
| $40.00/hr | Specialized Trades | $83,200 | $9,474 | $6,365 | $3,974 | $1,219 | $2,438 | $63,387 |
| $50.00/hr | Management / Engineering | $104,000 | $14,050 | $7,956 | $5,003 | $1,481 | $2,961 | $76,991 |
| $75.00/hr | Senior Leadership / Tech | $156,000 | $26,174 | $11,934 | $7,577 | $2,121 | $4,243 | $110,315 |
Form IL-W-4 State Withholding Certificate & Exemption Mechanics
Illinois employers calibrate state income tax withholding using Form IL-W-4 (Employee's Illinois Withholding Allowance Certificate) under 35 ILCS 5/702:
Enter 1 for yourself if no one else claims you as a dependent. Each basic allowance reduces annual taxable wages by $2,925 ($112.50 per bi-weekly paycheck).
Enter 1 for your spouse if married filing jointly and your spouse does not claim their own exemption on another Form IL-W-4, granting an additional $2,925 deduction.
Enter the number of qualifying dependents you claim on your federal income tax return. Each dependent adds an extra $2,925 annual allowance to lower state payroll withholding.
Enter additional allowances if you or your spouse are age 65 or older, or legally blind. Under 35 ILCS 5/204(c), each additional allowance provides an extra $1,000 exemption.
Elect a specific dollar amount (e.g. $25/paycheck) to be withheld extra to cover side freelance income, investments, or dual-earner phaseout under 35 ILCS 5/204(d).
Check exemption box only if you incurred zero tax liability last year and anticipate zero tax liability this tax year, or qualify under the Military Spouses Residency Relief Act.
Midwest Regional Paycheck Comparison ($100,000 Salary Single Filer)
See how Illinois' flat 4.95% rate compares against neighboring Midwestern states:
| Jurisdiction | Gross Salary | State & Local Tax | Federal & FICA | Annual Take-Home | Take-Home Delta |
|---|---|---|---|---|---|
| Illinois (Statewide) | $100,000 | $4,805 Flat (4.95%) | $20,820 | $74,375 | Baseline (Illinois 2026) |
| Indiana | $100,000 | $2,920 State (2.95%) + ~$1,500 County | $20,820 | $74,760 | +$385/yr in Indiana |
| Wisconsin | $100,000 | $4,980 Graduated (3.5%–7.65%) | $20,820 | $74,200 | -$175/yr in Wisconsin |
| Iowa | $100,000 | $3,190 Flat (3.80% in 2026) | $20,820 | $75,990 | +$1,615/yr in Iowa |
| Missouri | $100,000 | $4,120 Graduated (max 4.70%) | $20,820 | $75,060 | +$685/yr in Missouri |
| Kentucky | $100,000 | $3,382 Flat (3.50%) + Local Occ | $20,820 | $74,298 | -$77/yr in Kentucky |
Illinois Municipal Payroll Schedule (Chicago, Aurora, Naperville & Major Cities)
Under Illinois state law, municipalities and counties are prohibited from establishing municipal wage or local earned income taxes. Local wage withholdings across all cities are strictly 0.00%:
| City / Municipality | County Jurisdiction | Local Wage Tax | 2026 Wage Floor | Statutory Notes |
|---|---|---|---|---|
| Chicago | Cook County | 0.00% | $16.60/hr | Midwest financial center; 0.00% municipal income tax; $16.60/hr wage floor under BACP with One Fair Wage tip credit phaseout |
| Aurora | Kane & DuPage Counties | 0.00% | $15.00/hr | Fox Valley commercial & manufacturing center; zero municipal wage taxes |
| Naperville | DuPage & Will Counties | 0.00% | $15.00/hr | Technology corridor and corporate campus center; 0.00% local payroll withholding |
| Joliet | Will & Kendall Counties | 0.00% | $15.00/hr | Logistics and inland port transportation hub; zero local earned income tax |
| Rockford | Winnebago County | 0.00% | $15.00/hr | Aerospace and heavy manufacturing center; 0.00% municipal income tax |
| Springfield | Sangamon County | 0.00% | $15.00/hr | State capital & government administration center; zero local wage withholding |
| Peoria | Peoria County | 0.00% | $15.00/hr | Heavy equipment engineering & healthcare hub; 0.00% local earned income tax |
| Elgin | Kane & Cook Counties | 0.00% | $15.00/hr | Fox River manufacturing and healthcare center; 0.00% municipal wage tax |
Illinois Statutory Labor Regulations & Payroll Mandates (2026)
Illinois employers and workers are governed by the Illinois Department of Revenue, the Illinois Department of Labor, and the Illinois Compiled Statutes:
Under 35 ILCS 5/201 and IL Const. Art. IX, Illinois levies a flat 4.95% rate on taxable income with $2,925 basic exemptions ($5,850 MFJ). Under 35 ILCS 5/204(d), exemptions phase out completely to $0 if federal AGI exceeds $250k single / $500k married.
Under 820 ILCS 105/4, minimum wage is $15.00/hr ($9.00 tipped cash). The City of Chicago mandates $16.60/hr, with its One Fair Wage ordinance phasing out the tipped subminimum wage credit by 8% annually through 2028.
Under 820 ILCS 192/, employees earn up to 40 hours of paid leave per 12-month period (1 hour per 40 hours worked) for any reason. PLAWA is 100% employer-funded with $0.00 employee payroll deduction.
Municipal earned income taxes are prohibited statewide across all 102 counties. Employee SDI and PFML deductions are $0.00, and Illinois State Unemployment Insurance (SUTA) is 100% employer-funded.
Frequently Asked Questions: Illinois Paycheck Calculations (2026)
Authoritative answers on Illinois Department of Revenue rules, flat 4.95% tax rate, Form IL-W-4, and labor compliance:
Hiring or Working as a 1099 Contractor in Illinois?
Independent contractors in Illinois do not have state or federal taxes withheld by their hiring clients. Instead, 1099 independent workers pay federal self-employment tax (15.3% SECA) and submit quarterly estimated state income taxes directly to the Illinois Department of Revenue using Form IL-1040-ES (Estimated Income Tax Payments for Individuals). Illinois businesses paying non-corporate contractors $600 or more annually are legally required to obtain a signed Form W-9 before issuing payment to prevent mandatory 24% IRS backup withholding.
- Automatic Illinois state income tax withholding (flat 4.95%)
- Zero employee-paid SDI or PFML payroll deductions
- Employer pays 7.65% FICA match; covered by PLAWA paid leave & SUTA
- Zero payroll withholding; remit quarterly estimated taxes via Form IL-1040-ES
- Pays 15.3% Self-Employment Tax (SECA) on 92.35% of net profit
- Must provide signed Form W-9 to hiring businesses to avoid 24% backup tax
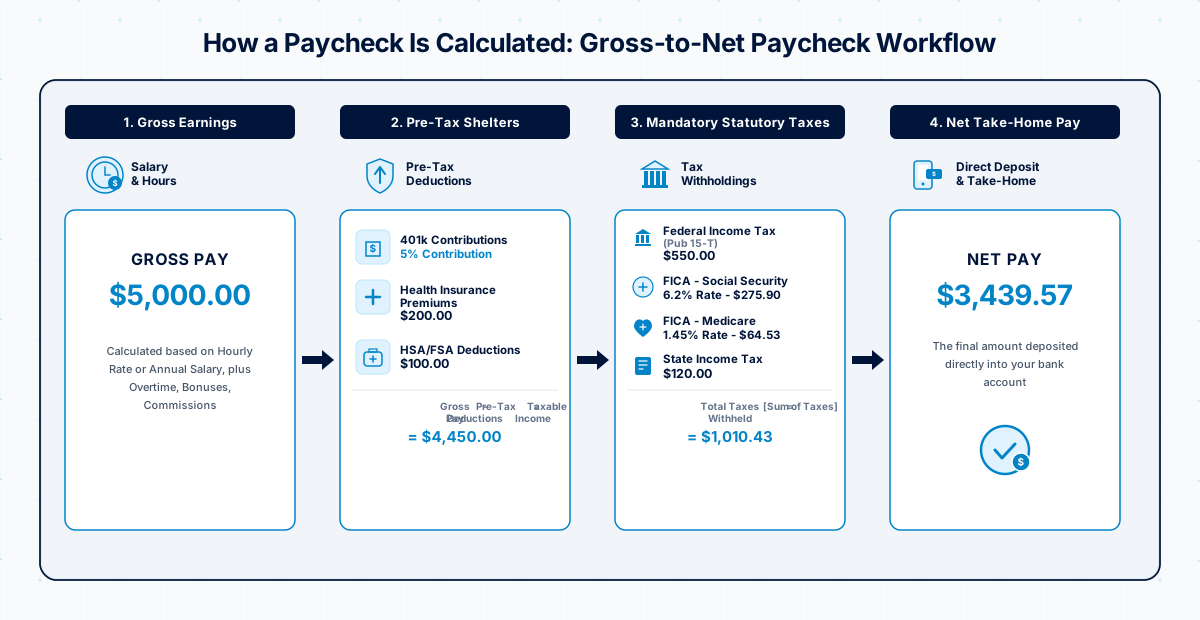
How It Works: The Gross-to-Net Paycheck Lifecycle
Understanding how gross compensation flows through pre-tax deductions, statutory FICA mandates, and federal/state withholding algorithms to reach your net direct deposit.
Gross Compensation
Total earnings agreed upon before any deductions, computed from annual base salary or hourly wage rate multiplied by regular and overtime hours worked.
Pre-Tax Shelters
Qualified IRC deductions including traditional 401(k), Section 125 health insurance, and HSAs subtracted first, shielding dollars from income tax liability.
Statutory Withholdings
Mandatory withholdings applied per IRS Pub 15 T (Federal Income Tax), 7.65% FICA (Social Security & Medicare), plus state and local municipal tax schedules.
Net Bank Deposit
The final spendable paycheck amount routed directly into your designated bank account via ACH direct deposit on your employer's scheduled pay frequency.
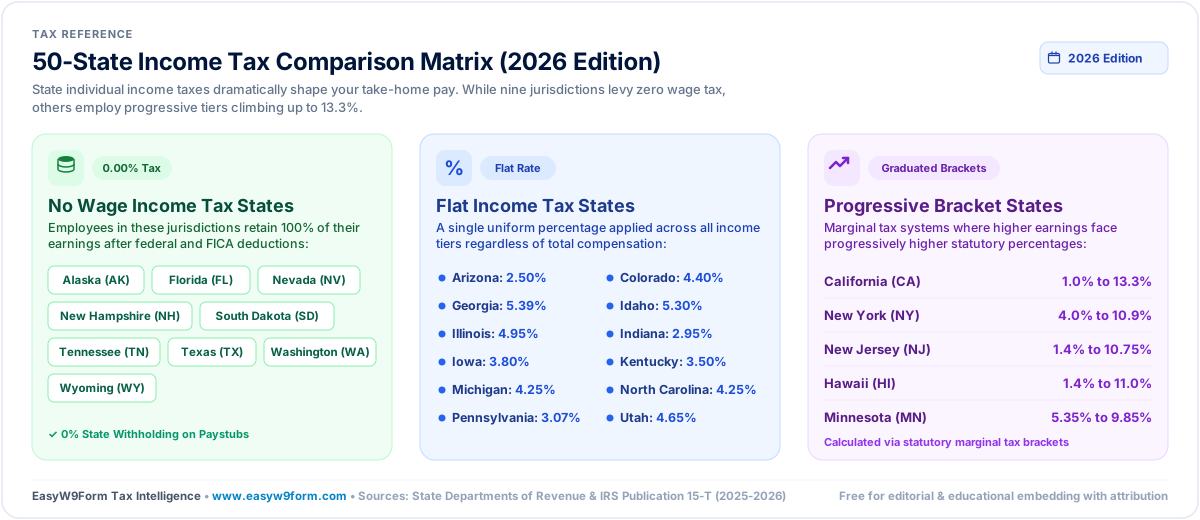
50-State Income Tax Comparison Matrix (2026 Edition)
The Anatomy of a Paycheck: What Every Deduction Means
Your pay stub is governed by Title 26 of the United States Code (Internal Revenue Code). Understanding statutory withholdings empowers taxpayers to prevent end-of-year tax shock, eliminate IRS underpayment penalties (IRC § 6654), and legally maximize cash flow.
FICA & Statutory Social Security
The Federal Insurance Contributions Act (FICA) levies two mandatory payroll deductions totaling 7.65% (learn more in our Paystub Tax Deductions Guide):
- 6.2% Social Security (OASDI): Applies strictly up to the annual statutory wage limit ($184,500 in 2026). Earnings above this threshold pay 0% Social Security tax.
- 1.45% Medicare (HI): Uncapped. Every dollar earned is subject to this base healthcare rate.
- 0.9% Additional Medicare: Mandated by the ACA for compensation exceeding $200,000 (Single) or $250,000 (Married Filing Jointly). Employers must withhold automatically once wages breach $200k.
Pre-Tax vs. Post-Tax Deductions
Not all deductions cost you dollar-for-dollar. See our guide to W-2 Box 12 Deduction Codes for reporting details:
Subtracted before federal and state income taxes are calculated. Contributing $100 typically only reduces your take-home pay by $72 to $78, delivering immediate 22%–28% statutory tax shielding.
Subtracted after all federal, state, and payroll taxes are computed. Contributing $100 reduces your paycheck by exactly $100 today, but enables tax-free distributions during retirement.
IRS Form W-4 Mechanics (Post-2020)
The IRS eliminated personal withholding allowances in 2020. Read our full IRS Form W-4 Guide or see W-9 vs. W-4 differences:
- Step 2 (Multiple Jobs): Accounts for a working spouse or secondary freelance job to prevent underwithholding into higher tax brackets.
- Step 3 (Dependents): Subtracts $2,200 per qualifying child (2026 OBBBA) directly from annual tax withholding, instantly boosting net pay per paycheck.
- Step 4(c) (Extra Withholding): Allows custom flat dollar deductions (e.g. $50/check) to offset investment earnings or 1099 side income.
6 Proven Strategies to Legally Boost Your Net Take-Home Pay
Rather than waiting 12 months for an IRS tax refund (which is effectively an interest-free loan to the federal government), use these statutory strategies to put more spendable cash into every paycheck.
Recalibrate Form W-4 Withholding
If you received a $3,600 IRS refund last April, you overwithheld roughly $300 every month. Submitting an updated Form W-4 with accurate deductions immediately reclaims that cash on every paycheck.
Maximize Triple-Advantaged HSAs
Health Savings Accounts (IRC § 223) avoid Federal Income Tax, State Income Tax, and FICA payroll tax (7.65%) when deducted via Section 125 cafeteria plans—beating 401(k) tax savings.
Audit Remote Work State Withholdings
Ensure your employer’s HR payroll software reflects your actual physical state of residence. Working remotely from Texas or Florida for a California firm shouldn't automatically incur CA withholding if you have no CA physical presence. Compare state rules on our 50-State Tax Guides.
Leverage Pre-Tax Commuter Benefits
IRC Section 132(f) permits up to $340/month in 2026 ($325/month in 2025) in pre-tax payroll transit and parking deductions. Paying for metro passes or garage parking via payroll directly slashes taxable gross wages.
Utilize Dependent Care FSAs
Allocate up to $5,000 per family into a Dependent Care Flexible Spending Account pre-tax for daycare, preschool, or eldercare expenses—generating up to $1,500+ in annual federal payroll tax savings.
Prepare for the Social Security “Pay Bump”
Earners making over $184,500 stop paying the 6.2% OASDI tax once their year-to-date earnings hit the wage base. Paychecks in late summer or autumn automatically surge by 6.2% until December 31. Check your effective brackets with our Federal Tax Bracket Engine.
Complementary IRS & Compliance Tools
Accelerate tax filing, contractor verification, and quarterly estimated prep.
Create official IRS Form W-9 PDFs with client-side cryptographic signatures.
Explore marginal vs effective federal tax rates for 2026 filings.
Calculate 15.3% SECA tax, business deductions, and quarterly vouchers.
Direct IRS and 50-state direct deposit statutory tracking portals.