Official Estimated Tax Liability Statement (Form 1040 & State Tax Return Synchronized)
Massachusetts Paycheck Calculator (2026 Take-Home Pay)
Calculate your exact net take-home salary in Massachusetts after Federal Income Tax, Massachusetts DOR flat 5.00% income tax (M.G.L. c. 62, § 4), 4.00% Fair Share Amendment surtax over $1,107,750, $4,400 personal exemption, 0.46% MA PFML (M.G.L. c. 175M), and 0% municipal taxes.
Paycheck Parameters
Adjust salary, frequency, filing status, and deductions.
Computes your true statutory income tax obligation by deducting the full standard deduction ($16,100 Single / $32,200 MFJ) upfront from annual gross pay before applying progressive tax brackets (identical to SmartAsset & Form 1040).
savingsPre-Tax Deductions (401k, Health, HSA / FSA)expand_more
tuneIRS Form W-4 Adjustments (Step 2c, Step 3 & Step 4c)expand_more
| Gross Earnings | $3,269.23 |
| Federal Income Tax (FIT) | -$379.62 |
| Social Security (6.2%) | -$202.69 |
| Medicare (1.45%) | -$47.40 |
| State Income Tax (MA) | -$155.00 |
| MA PFML (0.46%) | -$15.04 |
| Net Direct Deposit | $2,469.48 |
Live Step-by-Step Statutory Tax Audit & Mathematical Breakdown
See exactly how your $3,269.23 ($85,000.00/yr) gross pay converts to $2,469.48 take-home pay. Below is the unredacted, live mathematical calculation showing federal tax brackets, Massachusetts state deductions, and FICA mandates.
Key Takeaways & Take-Home Pay Insights
Effective Tax Rate Breakdown
On an $85,000 gross salary, estimated net take-home pay is approximately 75.5% (~$2,469.48 bi-weekly) after standard federal income tax, baseline state tax, and mandatory FICA contributions.
FICA OASDI Cap Threshold
The 6.2% Social Security tax ceases once cumulative wages reach $184,500 in 2026, delivering an automatic late-year take-home pay boost to high-earning professionals.
Pre-Tax Shelter Optimization
Contributing $100 to a traditional 401(k) or HSA typically reduces take-home net pay by only ~$70 to $78 while shielding taxable earnings from federal (and state, where applicable) income tax brackets, creating instant 22%–28%+ statutory tax leverage.
Form W-4 Precision
The redesigned post-2020 IRS Form W-4 eliminated personal allowances; claiming Step 3 dependent credits ($2,200 per child for 2026 under OBBBA) immediately reduces annual federal withholding dollar-for-dollar on every paycheck.
Massachusetts Paycheck Calculation & Tax Withholding Guide (2026)
Under M.G.L. c. 62, § 4, Massachusetts levies a flat 5.00% individual income tax rate on earned wages, supplemented by the Article XLIV Fair Share Amendment (4.00% surtax on taxable income over $1,107,750 in 2026). Rather than a standard deduction, Massachusetts enacts statutory personal exemptions ($4,400 Single / $8,800 Married Joint under M.G.L. c. 62, § 3), combined with mandatory 0.46% Massachusetts Paid Family and Medical Leave (PFML) (M.G.L. c. 175M), a $15.00/hr statewide minimum wage, and 0.00% municipal wage taxes across all 351 cities and towns:
Under M.G.L. c. 62, § 4, Massachusetts taxes earned wages at a uniform 5.00% rate. Taxable income over $1,107,750 (indexed for 2026) is subject to a 4% surtax (9.0% total).
Under M.G.L. c. 62, § 3, Massachusetts does not offer a standard deduction. Filers claim personal exemptions: $4,400 Single / $8,800 MFJ / $6,800 HOH.
Under M.G.L. c. 175M, employees contribute up to 0.46% (0.18% family + 0.28% medical) toward PFML, capped at the $184,500 wage base ($848.70 max/yr).
Under M.G.L. c. 151, § 1, statewide minimum wage is $15.00/hr ($6.75 tipped cash floor; $8.25 employer tip credit). Local municipal increases are preempted.
Boston, Cambridge, Worcester, Springfield, and all 351 cities and towns enforce strictly 0.00% local income taxes under Massachusetts General Laws.
Massachusetts Salary Paycheck Benchmarks (2026 Tax Year)
Estimated annual, monthly, and bi-weekly take-home pay for single filers claiming standard exemptions in Massachusetts. Deductions reflect 2026 Federal Income Tax, FICA (Social Security & Medicare), Massachusetts DOR State Income Tax (5.00% under M.G.L. c. 62, § 4 after the $4,400 personal exemption), and Massachusetts PFML (0.46% under M.G.L. c. 175M).
| Gross Salary | Federal Tax | FICA Taxes | MA State Tax (5%) | MA PFML (0.46%) | Total Deductions | Net Take-Home | Monthly Pay | Bi-Weekly | Retention |
|---|---|---|---|---|---|---|---|---|---|
| $30,000 | $1,420 | $2,295 | $1,280 | $138 | $5,133 | $24,867 | $2,072 | $956 | 82.9% |
| $40,000 | $2,620 | $3,060 | $1,780 | $184 | $7,644 | $32,356 | $2,696 | $1,244 | 80.9% |
| $50,000 | $3,820 | $3,825 | $2,280 | $230 | $10,155 | $39,845 | $3,320 | $1,533 | 79.7% |
| $60,000 | $5,020 | $4,590 | $2,780 | $276 | $12,666 | $47,334 | $3,945 | $1,821 | 78.9% |
| $70,000 | $6,570 | $5,355 | $3,280 | $322 | $15,527 | $54,473 | $4,539 | $2,095 | 77.8% |
| $80,000 | $8,770 | $6,120 | $3,780 | $368 | $19,038 | $60,962 | $5,080 | $2,345 | 76.2% |
| $90,000 | $10,970 | $6,885 | $4,280 | $414 | $22,549 | $67,451 | $5,621 | $2,594 | 74.9% |
| $100,000 | $13,170 | $7,650 | $4,780 | $460 | $26,060 | $73,940 | $6,162 | $2,844 | 73.9% |
| $125,000 | $18,734 | $9,563 | $6,030 | $575 | $34,902 | $90,099 | $7,508 | $3,465 | 72.1% |
| $150,000 | $24,734 | $11,475 | $7,280 | $690 | $44,179 | $105,821 | $8,818 | $4,070 | 70.5% |
| $175,000 | $30,734 | $13,388 | $8,530 | $805 | $53,457 | $121,544 | $10,129 | $4,675 | 69.5% |
| $200,000 | $36,734 | $14,339 | $9,780 | $849 | $61,702 | $138,298 | $11,525 | $5,319 | 69.1% |
| $250,000 | $51,304 | $15,514 | $12,280 | $849 | $79,947 | $170,053 | $14,171 | $6,541 | 68.0% |
Massachusetts Hourly Wage Paycheck Conversions (Full-Time • 2,080 Hours)
Wage conversion for hourly employees working full-time schedules (40 hours per week, 52 weeks per year) in Massachusetts. Accurately reflects the statutory $15.00/hr statewide minimum wage under M.G.L. c. 151, § 1.
| Hourly Rate | Gross Annual | Federal Tax | FICA Taxes | MA State Tax (5%) | MA PFML (0.46%) | Net Take-Home | Weekly Pay | Bi-Weekly Pay |
|---|---|---|---|---|---|---|---|---|
| $7.25/hr (Fed Floor) | $15,080 | $0 | $1,154 | $534 | $69 | $13,323 | $256 | $512 |
| $12.00/hr | $24,960 | $886 | $1,909 | $1,028 | $115 | $21,022 | $404 | $809 |
| $15.00/hr (MA Min) | $31,200 | $1,564 | $2,387 | $1,340 | $144 | $25,765 | $495 | $991 |
| $18.00/hr | $37,440 | $2,313 | $2,864 | $1,652 | $172 | $30,439 | $585 | $1,171 |
| $20.00/hr | $41,600 | $2,812 | $3,182 | $1,860 | $191 | $33,554 | $645 | $1,291 |
| $25.00/hr | $52,000 | $4,060 | $3,978 | $2,380 | $239 | $41,343 | $795 | $1,590 |
| $30.00/hr | $62,400 | $5,308 | $4,774 | $2,900 | $287 | $49,131 | $945 | $1,890 |
| $35.00/hr | $72,800 | $7,186 | $5,569 | $3,420 | $335 | $56,290 | $1,082 | $2,165 |
| $40.00/hr | $83,200 | $9,474 | $6,365 | $3,940 | $383 | $63,038 | $1,212 | $2,425 |
| $50.00/hr | $104,000 | $14,050 | $7,956 | $4,980 | $478 | $76,536 | $1,472 | $2,944 |
| $75.00/hr | $156,000 | $26,174 | $11,934 | $7,580 | $718 | $109,594 | $2,108 | $4,215 |
* Statutory Note: Under M.G.L. c. 151, § 1, the Massachusetts statewide statutory minimum wage is $15.00/hr ($6.75 tipped cash floor). Wage rates below $15.00/hr are shown strictly for federal comparison and are legally impermissible for non-exempt Massachusetts workers.
Massachusetts Municipalities Directory (0.00% Local Wage Tax Statewide)
Under Massachusetts General Laws, all 351 cities and towns are preempted from levying local earned income taxes, city wage withholding, or municipal payroll assessments.
| City / Municipality | County | Local Tax Rate | Economic Profile & Compliance Notes |
|---|---|---|---|
| Boston | Suffolk | 0.00% (No Wage Tax) | State capital, financial center, biotech hub; 0.00% municipal income tax |
| Worcester | Worcester | 0.00% (No Wage Tax) | Central MA healthcare, education & biotechnology hub; zero city wage tax |
| Springfield | Hampden | 0.00% (No Wage Tax) | Pioneer Valley commercial, financial, and manufacturing center; 0.00% local tax |
| Cambridge | Middlesex | 0.00% (No Wage Tax) | Kendall Square global biotechnology and life sciences center; zero city wage tax |
| Lowell | Middlesex | 0.00% (No Wage Tax) | Historic Merrimack Valley technology and university center; 0.00% local tax |
| Brockton | Plymouth | 0.00% (No Wage Tax) | South Shore commercial, logistics, and healthcare hub; 0.00% local tax |
| Quincy | Norfolk | 0.00% (No Wage Tax) | South Shore financial services and corporate office hub; zero local wage tax |
| Lynn | Essex | 0.00% (No Wage Tax) | North Shore manufacturing and aviation defense corridor; 0.00% municipal tax |
| New Bedford | Bristol | 0.00% (No Wage Tax) | Commercial fishing, offshore wind energy, and manufacturing hub; 0.00% tax |
| Newton | Middlesex | 0.00% (No Wage Tax) | MetroWest corporate, professional, and healthcare center; 0.00% local wage tax |
| Somerville | Middlesex | 0.00% (No Wage Tax) | High-growth technology, life sciences, and innovation district; zero city tax |
| Framingham | Middlesex | 0.00% (No Wage Tax) | MetroWest retail, corporate headquarters, and distribution corridor; 0.00% local tax |
| Statewide Baseline (All 351 Jurisdictions) | All Counties | 0.00% (No Wage Tax) | Massachusetts General Laws prohibit municipal earned income or local payroll taxes |
New England Regional Comparison: Massachusetts vs Neighboring States ($100,000 Salary)
Comparing net take-home pay for a $100,000 single salary across New England. Massachusetts’s flat 5.00% tax plus 0.46% PFML ($5,240 total state deduction) is compared against neighboring jurisdictions.
| Jurisdiction | Tax Structure & Mandatory Deductions | State Tax + Mandates | Fed Tax + FICA | Net Take-Home | Net Pay Difference |
|---|---|---|---|---|---|
| Massachusetts | 5.00% Flat + 0.46% PFML | $5,240 | $20,820 | $73,940 | $0 (Baseline) |
| New Hampshire | 0.00% (No Income Tax) | $0 | $20,820 | $79,180 | +$5,240 |
| Rhode Island | 3.75% – 5.99% + 1.2% TDI | $5,235 | $20,820 | $73,945 | +$5 |
| Connecticut | 2.00% – 6.99% + 0.5% CTPL | $5,045 | $20,820 | $74,135 | +$195 |
| Maine | 5.80% – 7.15% + 0.5% PFML | $6,036 | $20,820 | $73,144 | -$796 |
| Vermont | 3.35% – 8.75% (Graduated) | $4,750 | $20,820 | $74,430 | +$490 |
| New York (Non-NYC) | 4.00% – 10.90% + PFL | $5,316 | $20,820 | $73,864 | -$76 |
Form M-4 Mechanics, Personal Exemptions & Interstate Taxation
Form M-4 Withholding Exemption Certificates
Because Massachusetts did not conform to the 2020 federal Form W-4 redesign, the Department of Revenue requires employees to complete Form M-4 (Massachusetts Employee\'s Withholding Exemption Certificate). Form M-4 establishes personal exemptions: $4,400 for Single filers and $8,800 for Married Couples, plus $1,000 per dependent. If an employee fails to complete Form M-4 upon hire, Massachusetts law mandates withholding at Single with zero exemptions.
Personal Exemptions vs. Standard Deduction
Unlike federal law or states that provide a standard deduction, Massachusetts enacts statutory personal exemptions under M.G.L. c. 62, § 3 ($4,400 Single / $8,800 Married Joint / $6,800 Head of Household). Taxpayers take these exemptions directly against earned wages before the flat 5.00% rate is calculated. High earners earning over $1,107,750 in 2026 ($1,083,150 in 2025; indexed for inflation) are subject to the Article XLIV Fair Share 4% surtax on excess taxable income.
Interstate Commuters (No Reciprocity)
Massachusetts does NOT maintain reciprocity agreements with neighboring states like New Hampshire, Rhode Island, Connecticut, or Vermont. Nonresidents who physically perform work in Massachusetts (such as New Hampshire residents commuting to Boston) owe Massachusetts state income tax on all wages earned within the Commonwealth and must file Form 1-NR/PY annually. Additionally, Massachusetts commuters (both residents and nonresidents) can claim a state tax deduction under M.G.L. c. 62, § 3(B)(a)(15) (Form 1 Schedule Y) for MBTA transit passes and E-ZPass tolls exceeding $150 up to $750/year.
W-2 Employee vs. 1099 Independent Contractor Compliance in Massachusetts
Massachusetts enforces one of the strictest worker classification statutes in the nation under M.G.L. c. 149, § 148B (the three-prong Independent Contractor ABC test):
- Employer withholds Federal Income Tax & FICA (7.65%).
- Employer withholds MA state tax (5.00%) & MA PFML (0.46%).
- Employer pays matching 7.65% FICA, workers’ comp, and SUTA unemployment.
- Protected by Massachusetts Minimum Wage ($15.00/hr) and 1.5x weekly overtime.
- Receives Form W-2 by January 31 annually.
- Must satisfy all 3 prongs of M.G.L. c. 149, § 148B to be classified as 1099.
- Receives 100% gross compensation with zero employer payroll tax withholdings.
- Responsible for full 15.3% federal self-employment tax (SECA: OASDI + Medicare).
- Must remit quarterly estimated Massachusetts income taxes on Form 1-ES.
- Must provide signed Form W-9 to client prior to invoice disbursement.
Frequently Asked Questions: Massachusetts Paycheck & Tax Withholding
How It Works: The Gross-to-Net Paycheck Lifecycle
Understanding how gross compensation flows through pre-tax deductions, statutory FICA mandates, and federal/state withholding algorithms to reach your net direct deposit.
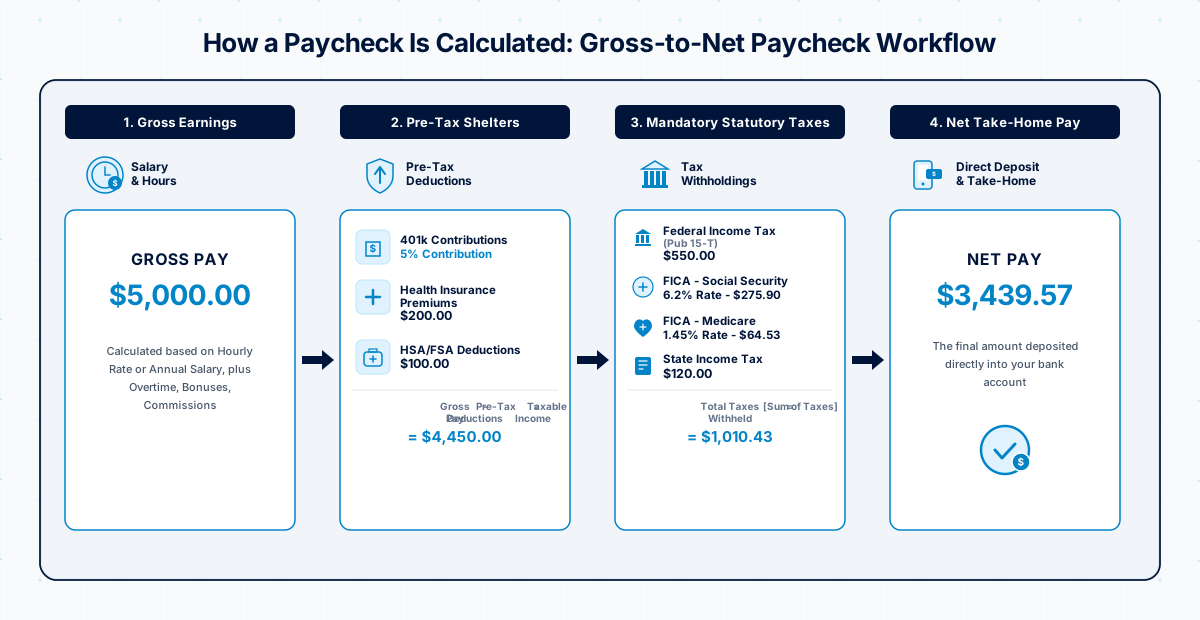
Gross Compensation
Total earnings agreed upon before any deductions, computed from annual base salary or hourly wage rate multiplied by regular and overtime hours worked.
Pre-Tax Shelters
Qualified IRC deductions including traditional 401(k), Section 125 health insurance, and HSAs subtracted first, shielding dollars from income tax liability.
Statutory Withholdings
Mandatory withholdings applied per IRS Pub 15 T (Federal Income Tax), 7.65% FICA (Social Security & Medicare), plus state and local municipal tax schedules.
Net Bank Deposit
The final spendable paycheck amount routed directly into your designated bank account via ACH direct deposit on your employer's scheduled pay frequency.
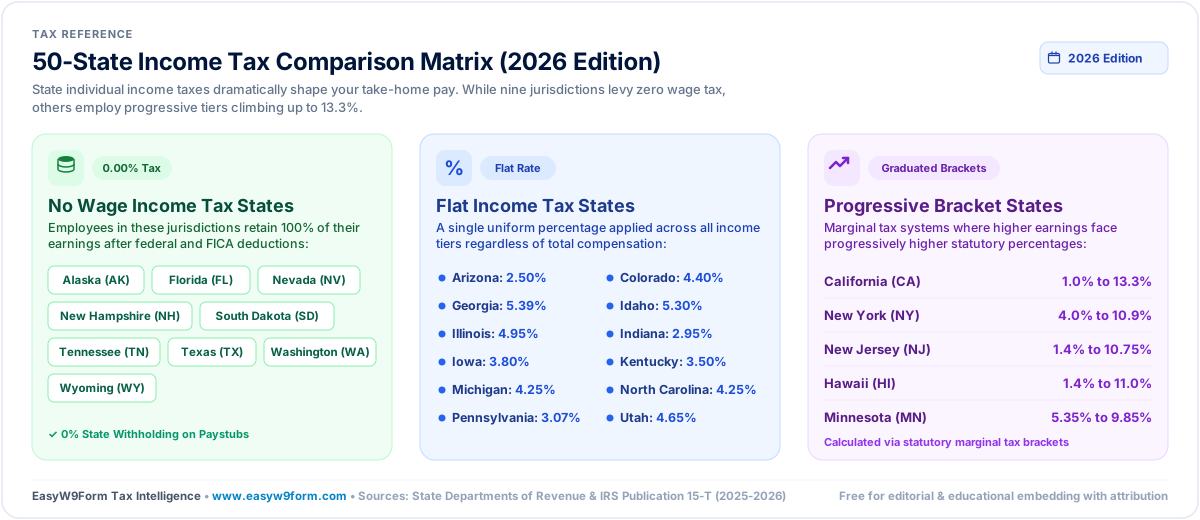
50-State Income Tax Comparison Matrix (2026 Edition)
The Anatomy of a Paycheck: What Every Deduction Means
Your pay stub is governed by Title 26 of the United States Code (Internal Revenue Code). Understanding statutory withholdings empowers taxpayers to prevent end-of-year tax shock, eliminate IRS underpayment penalties (IRC § 6654), and legally maximize cash flow.
FICA & Statutory Social Security
The Federal Insurance Contributions Act (FICA) levies two mandatory payroll deductions totaling 7.65% (learn more in our Paystub Tax Deductions Guide):
- 6.2% Social Security (OASDI): Applies strictly up to the annual statutory wage limit ($184,500 in 2026). Earnings above this threshold pay 0% Social Security tax.
- 1.45% Medicare (HI): Uncapped. Every dollar earned is subject to this base healthcare rate.
- 0.9% Additional Medicare: Mandated by the ACA for compensation exceeding $200,000 (Single) or $250,000 (Married Filing Jointly). Employers must withhold automatically once wages breach $200k.
Pre-Tax vs. Post-Tax Deductions
Not all deductions cost you dollar-for-dollar. See our guide to W-2 Box 12 Deduction Codes for reporting details:
Subtracted before federal and state income taxes are calculated. Contributing $100 typically only reduces your take-home pay by $72 to $78, delivering immediate 22%–28% statutory tax shielding.
Subtracted after all federal, state, and payroll taxes are computed. Contributing $100 reduces your paycheck by exactly $100 today, but enables tax-free distributions during retirement.
IRS Form W-4 Mechanics (Post-2020)
The IRS eliminated personal withholding allowances in 2020. Read our full IRS Form W-4 Guide or see W-9 vs. W-4 differences:
- Step 2 (Multiple Jobs): Accounts for a working spouse or secondary freelance job to prevent underwithholding into higher tax brackets.
- Step 3 (Dependents): Subtracts $2,200 per qualifying child (2026 OBBBA) directly from annual tax withholding, instantly boosting net pay per paycheck.
- Step 4(c) (Extra Withholding): Allows custom flat dollar deductions (e.g. $50/check) to offset investment earnings or 1099 side income.
6 Proven Strategies to Legally Boost Your Net Take-Home Pay
Rather than waiting 12 months for an IRS tax refund (which is effectively an interest-free loan to the federal government), use these statutory strategies to put more spendable cash into every paycheck.
Recalibrate Form W-4 Withholding
If you received a $3,600 IRS refund last April, you overwithheld roughly $300 every month. Submitting an updated Form W-4 with accurate deductions immediately reclaims that cash on every paycheck.
Maximize Triple-Advantaged HSAs
Health Savings Accounts (IRC § 223) avoid Federal Income Tax, State Income Tax, and FICA payroll tax (7.65%) when deducted via Section 125 cafeteria plans—beating 401(k) tax savings.
Audit Remote Work State Withholdings
Ensure your employer’s HR payroll software reflects your actual physical state of residence. Working remotely from Texas or Florida for a California firm shouldn't automatically incur CA withholding if you have no CA physical presence. Compare state rules on our 50-State Tax Guides.
Leverage Pre-Tax Commuter Benefits
IRC Section 132(f) permits up to $340/month in 2026 ($325/month in 2025) in pre-tax payroll transit and parking deductions. Paying for metro passes or garage parking via payroll directly slashes taxable gross wages.
Utilize Dependent Care FSAs
Allocate up to $5,000 per family into a Dependent Care Flexible Spending Account pre-tax for daycare, preschool, or eldercare expenses—generating up to $1,500+ in annual federal payroll tax savings.
Prepare for the Social Security “Pay Bump”
Earners making over $184,500 stop paying the 6.2% OASDI tax once their year-to-date earnings hit the wage base. Paychecks in late summer or autumn automatically surge by 6.2% until December 31. Check your effective brackets with our Federal Tax Bracket Engine.
Complementary IRS & Compliance Tools
Accelerate tax filing, contractor verification, and quarterly estimated prep.
Create official IRS Form W-9 PDFs with client-side cryptographic signatures.
Explore marginal vs effective federal tax rates for 2026 filings.
Calculate 15.3% SECA tax, business deductions, and quarterly vouchers.
Direct IRS and 50-state direct deposit statutory tracking portals.